Car Financing Credit Score Guide in Lee's Summit, MO
See the credit score tiers Lee's Summit, MO lenders use to set auto loan rates, how brackets work, and what score you actually need to finance a car.
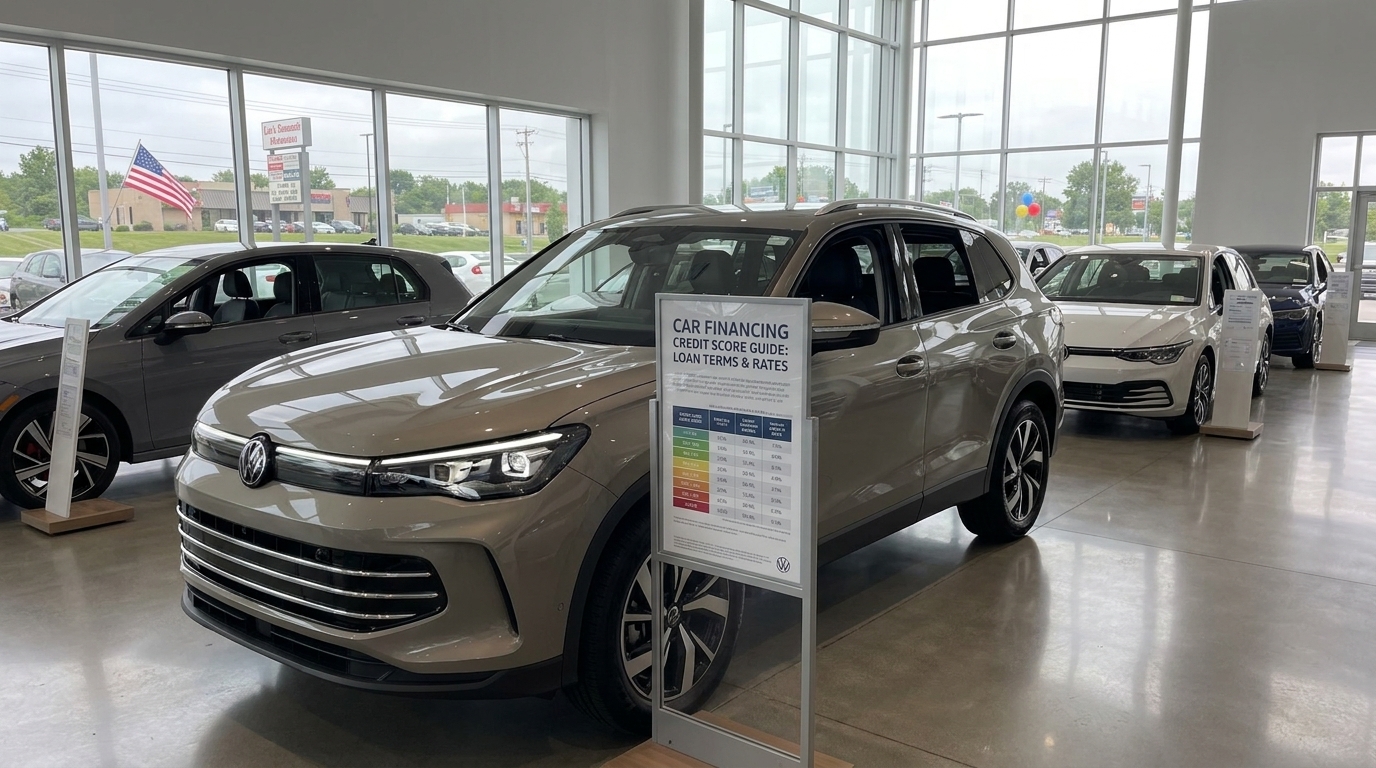
In Lee's Summit, MO, most lenders will approve a car loan starting around a 580 FICO score, but the rate you're offered is set by which credit tier you land in — typically Super Prime (781+), Prime (661-780), Near Prime (601-660), Subprime (501-600), and Deep Subprime (300-500). You don't need perfect credit to get financed; you need to understand which bracket your score sits in and how lenders price each one.
What credit score do you actually need to finance a car in Lee's Summit, MO?
You can generally finance a car in Lee's Summit with a FICO score of 580 or higher through mainstream lenders, and specialty subprime lenders will often work with scores in the 500s. A score of 661 or above (Prime tier) is the threshold where interest rates drop meaningfully and approval becomes routine rather than case-by-case.
The number itself matters less than the tier it puts you in. Lenders don't price loans on a sliding scale — they price them in brackets, and a 660 and a 665 can see materially different rates because they sit on opposite sides of a tier line.
How do lenders actually set auto loan rate brackets?
Auto lenders use a tiered credit system built on FICO Auto Score 8 or 9 (a version weighted toward auto-payment history), then assign each application to a bracket that maps to a specific rate range. Your bracket — not your exact score — determines the APR you're quoted, your down payment requirement, and your maximum loan term.
Here's the standard framework most banks, credit unions, and captive lenders (like Volkswagen Credit) use in the Lee's Summit market:
| Credit Tier | FICO Range | Typical New-Car APR (2026) | What to Expect |
|---|---|---|---|
| Super Prime | 781-850 | 5.0%-6.5% | Best rates, promotional APRs, minimal down payment |
| Prime | 661-780 | 6.5%-8.5% | Standard approvals, competitive terms |
| Near Prime | 601-660 | 9.0%-12.5% | Approval likely, higher rate, larger down payment |
| Subprime | 501-600 | 13%-18% | Specialty lender, proof of income required |
| Deep Subprime | 300-500 | 18%-21%+ | Limited options, significant down payment expected |
These ranges shift with the federal funds rate, but the tier structure itself is stable. The team at Volkswagen Lee's Summit works with a network of banks, credit unions, and Volkswagen Credit to shop applications across multiple lenders — which matters, because two lenders looking at the same 640 score can place you in different tiers based on their own risk models.
Why does the same score get different rates at different dealers?
The same credit score gets different rates because each lender sets its own tier cutoffs, and each dealership works with a different lender network. One bank's Prime tier may start at 661; another's may start at 680. The score is a constant — the tier assignment is not.
This is why pre-approval matters. When Volkswagen Lee's Summit submits your application, it goes to multiple lending partners simultaneously, and the finance team sees which lender placed you in the most favorable bracket. A shopper who walks into a single-lender situation only sees one answer.
What factors beyond credit score affect your car loan approval?
Beyond your FICO score, auto lenders weigh five specific factors: debt-to-income ratio (ideally under 40%), payment-to-income ratio (target 15% or less), length of employment, down payment size, and the loan-to-value ratio on the vehicle itself. A strong showing on these can lift you into a better tier even with a middling score.
Down payment is the fastest lever. Putting 15-20% down on a used vehicle or 10% on a new one reduces the lender's risk exposure and often moves a borderline application from Near Prime to Prime pricing. On a $30,000 loan, that shift can save you $3,000-$5,000 over a 60-month term.
The vehicle also matters. Newer, lower-mileage cars carry lower rates than older used cars because the collateral holds its value longer. A Certified Pre-Owned Volkswagen — inspected, warranty-backed, typically under six model years old — often qualifies for CPO-specific financing rates that sit between new-car and standard used-car pricing.
How can you improve your credit tier before applying in 2026?
You can move up a credit tier in 30-60 days by paying down revolving credit card balances below 30% of your limit, disputing any inaccurate items on your credit report, and avoiding new credit applications in the 90 days before you shop. These three moves target the factors that shift fastest on FICO models.
Credit utilization alone accounts for 30% of your FICO score. If you're carrying $4,500 on a $5,000 limit card, paying that down to $1,500 before your statement closes can lift your score 20-40 points — often enough to cross a tier line. For a Lee's Summit buyer sitting at 655, that jump into Prime territory can be worth several thousand dollars in interest over the loan.
If your score is in the low 600s or below, consider a co-signer with strong credit. The lender uses the higher of the two scores for tier placement, which can dramatically change the rate offered.
What if your credit score is below 600?
If your score is below 600, you can still finance a car in Lee's Summit through subprime auto lenders, but expect a higher APR (typically 13%-21%), a required down payment of $1,500-$3,000 or more, and a shorter loan term. Approval will depend on verifiable income, stable employment history, and residential stability.
Subprime lenders look at the whole picture, not just the number. Two years at the same job, a checking account without recent overdrafts, and a utility bill in your name at a Lee's Summit address all strengthen the file. Buyers in the Summit Fair or Longview area sometimes assume a low score means no car — it usually just means a different lender and a shorter path to refinancing once you've built 12 months of on-time payments.
How does Missouri sales tax and titling affect what you finance?
In Missouri, you pay state sales tax (4.225%) plus local Jackson County and Lee's Summit taxes when you title the vehicle at the Department of Revenue — not at the dealership. Missouri also allows a trade-in tax credit, meaning you only pay sales tax on the difference between the new vehicle price and your trade-in value.
This matters for financing because you have 30 days from the purchase date to title and pay taxes in Missouri. Many Lee's Summit buyers roll the estimated tax and title fees into the loan so they arrive at the license office with the payment ready. Ask your finance manager to structure this explicitly — it prevents a surprise out-of-pocket bill and keeps your loan-to-value ratio accurate.
Frequently Asked Questions
Can I finance a Volkswagen with a 550 credit score in Lee's Summit?
Yes, financing with a 550 score is possible through subprime lenders that Volkswagen Lee's Summit works with, though you should expect an APR in the 15%-19% range, a down payment of at least $2,000, and proof of steady income. A co-signer with stronger credit can significantly improve your rate and approval odds.
What credit score qualifies for 0% APR Volkswagen financing?
Promotional 0% APR offers from Volkswagen Credit typically require a Super Prime credit score of 781 or higher, plus meeting specific vehicle, model-year, and term-length conditions. These offers rotate by model and month, so confirm current eligibility with the finance team at Volkswagen Lee's Summit before assuming you qualify.
Does getting pre-approved hurt my credit score?
A pre-approval triggers a hard credit inquiry, which can lower your score by 3-5 points temporarily. However, FICO treats multiple auto-loan inquiries within a 14-day window as a single inquiry, so shopping several lenders in a short period costs you the same as checking with one. The rate savings almost always outweigh the small score dip.
How much should I put down on a car in Lee's Summit?
Aim for 10% down on a new vehicle and 15-20% on a used vehicle. On a $30,000 purchase, that's $3,000-$6,000. A larger down payment lowers your loan-to-value ratio, reduces your monthly payment, protects against negative equity, and often moves borderline applications into a better credit tier with a lower APR.
Can I refinance my car loan after my credit improves?
Yes. Once you've made 12 months of on-time payments and your credit score has improved by 40+ points, refinancing can meaningfully lower your APR and monthly payment. Many Lee's Summit buyers who start in Subprime or Near Prime tiers refinance into Prime rates within 18-24 months, saving thousands over the loan's remaining life.
Do credit unions in Lee's Summit offer better rates than dealer financing?
Credit unions often advertise lower base rates, but dealer financing through Volkswagen Lee's Summit shops your application across multiple banks and captive lenders at once, which can beat a single credit union quote — especially on new vehicles with manufacturer incentives. The right answer is to compare both; bring your credit union's pre-approval to the dealership and let the finance team try to beat it.
The bottom line on credit and car financing in Lee's Summit
Your credit score matters, but the tier it lands you in matters more. Understanding where 661, 601, and 781 sit on the lender's bracket map lets you make specific moves — paying down a card, adding a down payment, bringing a co-signer — that translate directly into a lower APR rather than vague credit-improvement advice.
Volkswagen Lee's Summit carries a 4.5-star rating across more than 5,100 Google reviews, with customers consistently noting a transparent, straightforward finance process. Buyers in Lee's Summit, MO who want a clear read on which tier they qualify for — and what that means for their monthly payment — can start a pre-approval at https://www.vwleessummit.com and have the numbers in hand before setting foot on the lot.