Car Dealership Financing Options in Independence, Missouri: What to Expect in 2026
A 2026 guide to car dealership financing in Independence, MO — current APR ranges, local dealer options, BHPH alternatives, and what buyers should know.
If you're shopping for a vehicle in Independence, Missouri, the financing conversation often matters more than the sticker price. The APR you qualify for, the term you choose, and the incentives available in the Kansas City metro can shift your total cost by thousands of dollars over the life of the loan. Understanding the current rate environment — and how local dealership financing actually works — puts you in a stronger position before you sign anything.
Here's what auto financing looks like in Independence in 2026, what rates qualified buyers are seeing, and how to think about the choices in front of you.
The Current Auto Loan Rate Environment in Independence
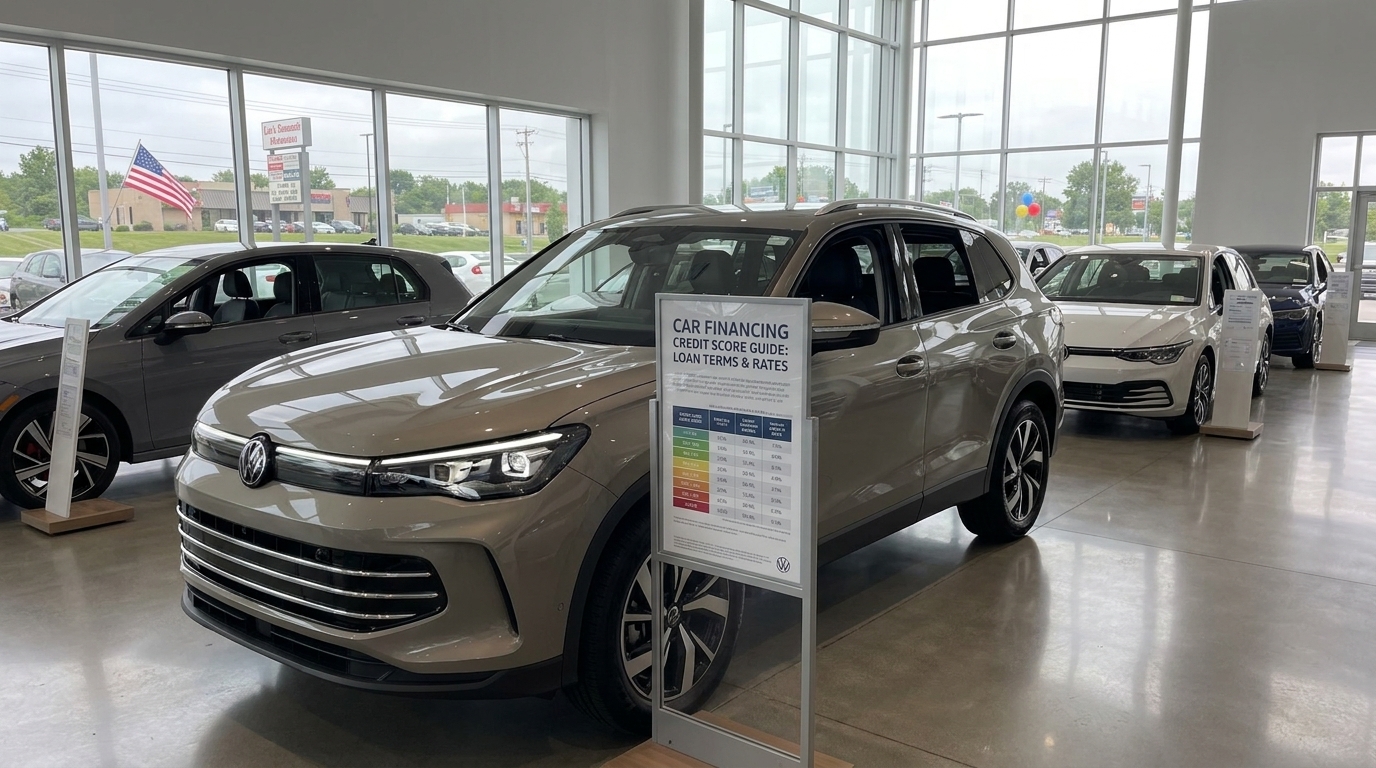
As of August 2026, the lowest new-car APR available to the best-qualified buyers from credit unions serving Independence is approximately 3.75%, according to regional lender comparisons. That figure represents the floor — it generally requires top-tier credit, a strong loan-to-value ratio, and a lender relationship with favorable terms for your profile.
For buyers with more typical credit profiles, the picture is different. The median new-car APR across credit unions serving Independence runs around 5.20%, while buyers with challenged credit can face rates as high as 13.00% through subprime or buy-here-pay-here financing. Used-vehicle financing starts around 4.09% at credit unions for well-qualified buyers — but that floor rises quickly as credit scores fall. That spread between the best and worst available rates is one of the most important numbers for Independence shoppers to internalize: who you are to a lender matters as much as the vehicle you're buying.
Independence sits within the broader Kansas City metro, which means buyers here benefit from a competitive multi-dealer market across the area. Manufacturer incentives are regionalized — the same model can carry different APR specials and cash rebates in Independence than it does even a few hours away. That regional layer is why entering your local ZIP on a manufacturer's offers page matters more than relying on national advertising.
How Loan Term Shapes Your Monthly Payment
Term length is where many buyers in Independence either save money or quietly overpay. The relationship between rate and term is consistent across lenders: longer terms carry higher APRs because the lender's risk window is longer and the collateral depreciates faster than the principal balance falls.
Stretching to 72 or 84 months to chase a lower monthly payment can leave you upside-down on the loan well into year three or four — a particularly painful position if you commute long distances on I-70 or US-24 and rack up miles quickly.
If your budget can absorb it, a 60-month term is often the more disciplined choice for new vehicles in this market. Shorter terms typically reward you with lower APRs, and you build equity faster.
Captive Lenders, Banks, and Credit Unions
Dealership financing in Independence typically routes through one of three channels:
Captive lenders
These are the manufacturer's own financing arms (Volkswagen Credit, Ford Motor Credit, Toyota Financial Services, and so on). Captive lenders are the source of subsidized promotional APRs — the low-rate offers you see advertised on specific new models. These programs are tied to particular trims, model years, and credit tiers, and they change monthly.
Banks and credit unions
National and regional banks plus Kansas City–area credit unions compete heavily for auto loans. Independence buyers often secure pre-approval from a credit union before visiting a dealership, which gives them a benchmark rate to compare against any dealer-arranged financing. Credit unions serving Independence are currently among the most competitive local sources, with new-car rates starting at 3.75% for top-tier borrowers.
Dealership-arranged financing
When you finance through the dealership, the dealer typically submits your application to multiple lenders and presents you with the approved offers. A well-run finance office can often beat the rate you walked in with, particularly when a captive incentive is active on the model you're buying.
Buy-Here-Pay-Here Options for Subprime Buyers
For Independence buyers with damaged credit, no credit history, or a past repossession, traditional bank financing may not be available. Auto Now (10500 E US-24) operates in Independence as a buy-here-pay-here (BHPH) option, approving buyers based on income and down payment rather than credit score. Auto Now includes a 24-month/24,000-mile warranty on all vehicles with buy-here-pay-here financing. Landmark CDJR (1900 S Noland Rd) also offers pre-approved financing for bad credit, no credit, and bankruptcy situations through its credit approval department.
BHPH financing is structured differently from traditional loans — terms are typically shorter, payments are often weekly or bi-weekly, and rates run toward the upper end of the market, reaching as high as 13.00% APR for challenged credit profiles. For buyers who genuinely have no other path to a vehicle, BHPH can be a bridge, but it's worth exhausting credit union and subprime bank options first.
Missouri-Specific Considerations for Independence Buyers
A few practical points matter for anyone financing a vehicle in Jackson County:
- Sales tax is paid at registration, not at the dealership. Missouri buyers handle state and local sales tax when they title the vehicle through the Missouri Department of Revenue, typically within 30 days of purchase. Plan for this as a separate cash outlay rather than rolling it into the loan blindly.
- Trade-in tax credit applies in Missouri. The taxable amount on your new vehicle is reduced by the trade-in allowance, which can meaningfully lower the tax bill if you're trading a vehicle of substantial value.
- Personal property tax is annual. Jackson County assesses personal property tax on vehicles each year — a holding cost separate from your loan payment that many newcomers to Missouri underestimate.
- Missouri law requires financing disclosures. Before signing, lenders must disclose the APR, minimum down payment, and number of payments — giving you a clear picture of the total obligation.
Because tax and registration costs are paid outside the loan, your monthly payment quote at the dealership won't reflect the full out-of-pocket picture. Build those numbers into your budget before deciding what monthly payment you can actually carry.
Current Incentives Worth Checking
Manufacturer incentive programs in 2026 continue to include promotional APR offers on select new models for top-tier credit, cash rebates, bonus cash, conquest and loyalty incentives, and programs for recent college graduates and military members. These stack and expire on different schedules, so the right move is to check each manufacturer's official offers page using an Independence ZIP code shortly before you buy. Manufacturer-specific subsidized APR programs were not uniformly available across all brands in this market as of late August 2026, so confirming current offers directly with the dealer or manufacturer is essential.
Frequently Asked Questions
What credit score do I need for the best auto loan rates in Independence?
The lowest available new-car rates — currently around 3.75% APR from credit unions serving Independence — generally require excellent credit and a strong borrower profile. As your credit score declines, rates rise toward the market median of around 5.20% and can reach as high as 13.00% for buyers with significantly challenged credit.
Is it better to get pre-approved before visiting a dealership?
Pre-approval from a credit union or bank gives you a benchmark rate and strengthens your negotiating position. The dealership finance office may still beat it — particularly if a captive incentive is active — but you'll know whether the dealer's offer is actually competitive.
Can I finance a used car at the same rate as a new car?
Generally no. Used-car APRs tend to run higher than new-car rates because lenders view used collateral as higher risk. Credit unions in Independence start used-car financing around 4.09% for well-qualified buyers, but that floor rises with credit risk, just as it does for new vehicles.
What if I have bad credit or no credit?
Subprime lenders and buy-here-pay-here dealers like Auto Now serve Independence buyers who don't qualify for traditional financing. Landmark CDJR also offers pre-approved financing for bad credit, no credit, and bankruptcy situations. Rates will be higher — up to 13.00% APR — so use these options strategically and look to refinance with a traditional lender once your credit improves.
How do Independence dealerships compare to online lenders for auto financing?
Online lenders can be competitive benchmarks, but local dealerships in Independence — particularly those working with multiple lenders and captive financing arms — can sometimes match or beat online offers, especially when manufacturer incentive programs are active. The practical advantage of dealer-arranged financing is speed and convenience; the risk is accepting a rate without a pre-approval comparison in hand.
Does rolling sales tax into my auto loan make sense in Missouri?
Because Missouri sales tax is paid at registration rather than at the dealership, it isn't automatically included in your dealer-arranged loan. Some buyers choose to finance that cost separately or pay it out of pocket. Rolling any amount into a loan extends the principal you're paying interest on, so the lower your APR and the shorter your term, the less it costs you to finance that outlay.
Putting It Together
Financing a vehicle in Independence in 2026 is fundamentally about matching the right lender, term, and incentive to your credit profile — not about chasing the lowest advertised number. The buyers who do best in this market tend to walk in with a pre-approval in hand, a clear sense of the term they want, and an understanding of which manufacturer incentives apply to the model they're considering.
— and another described the experience as "clean, smooth, and easy." Independence-area shoppers who want help working through captive financing programs, current Volkswagen incentives, and the regional offers available in the Kansas City metro can reach Volkswagen Lee's Summit at https://www.vwleessummit.com to review options and structure a loan that fits the budget.